
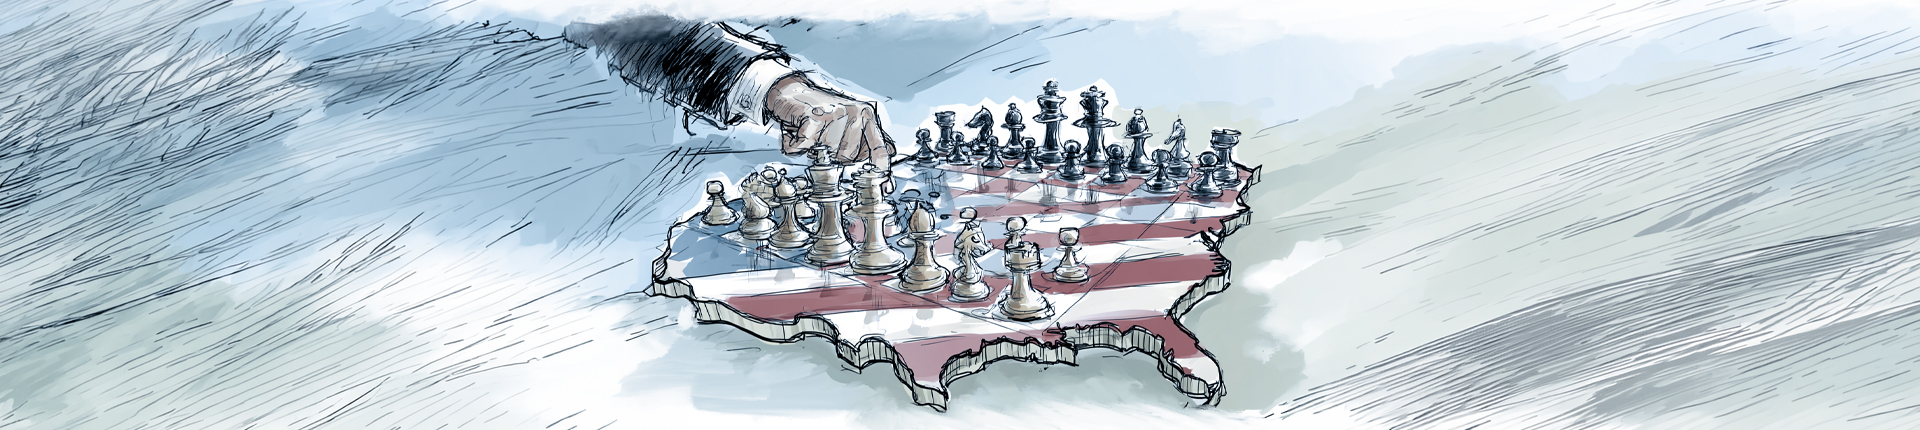

The Pentagon is the largest shareholder of the only fully integrated rare earth producer in the United States. It holds approximately 15% of MP Materials and has committed to purchasing the output of the company’s new magnet factory, including a minimum price guarantee.
Government ownership, a government purchase guarantee, and a government price floor: these three instruments – which a free-market economy does not provide for – are all part of a single transaction under a Republican administration.
That sounds like more government, bureaucracy, and regulation. But in fact, 2026 is likely to be one of the least regulated years in American history. The spring regulatory agenda alone calls for the record repeal of 702 existing regulations. And for every new rule, ten are to be repealed. Measured by the number of regulations, the government is thus shrinking.
In return, it is growing in other areas – namely, where it carries more economic weight: as an owner, tax collector, price setter, and allocator.
The government as owner
Washington currently holds approximately 30 corporate investments worth about $26.7 billion: just under a 10% stake in Intel through converted CHIPS Act grants, as well as stakes in nine quantum computing and commodities companies, such as Lithium Americas and Trilogy Metals. When U.S. Steel was sold, the government retained a “golden share” – a permanent veto right against plant closures and the relocation of production overseas. However, there is no consolidated public registry of this portfolio.
The government as a tax collector
The average tariff rate on U.S. imports has risen from about 1.5% (2022) to 11% (2026) – the highest level since 1943. This represents the largest tax increase since 1993 relative to gross domestic product, amounting to about $1,500 per household in 2026. These tariffs were imposed without a single piece of legislation from Congress. Added to this is an unprecedented arrangement: Nvidia is allowed to export to China in exchange for a 25% levy.
The state as price setter
The Department of Energy is maintaining more than twenty emergency orders that keep unprofitable coal-fired power plants online against the wishes of the operators and the relevant states. These plants account for less than 1% of U.S. coal consumption. The orders force the continued operation of uneconomical plants and disrupt orderly investment planning. The resulting additional costs, running into the millions, are borne by electricity customers.
The state as allocator
Export licenses determine, on a case-by-case basis, who is permitted to purchase which computing power. In June, a letter from the Ministry of Commerce removed two leading AI models from the global market within two hours, without a regulation or justification; the order was rescinded after two and a half weeks. Access is determined not by price, but by authorization.
The objection that this is nothing new is valid: for Republicans, the “lean government” has always been more of a rallying cry than an actual reality. Consider Nixon’s wage and price controls, TARP and Medicare Part D under Bush, or the agricultural subsidies that have outlasted every Republican majority in the postwar era.
The difference from today lies not in the intervention itself, but in its form. Those programs were crisis-driven, enacted by Congress, and temporary. Today’s tools are executive in nature, crisis-free, and have no expiration date. This concentration of power will become permanent because, at the end of June, the Supreme Court struck down the protection against dismissal for members of independent agencies: Regulators who previously operated at a distance from the White House can now be removed at any time – and are thus, in effect, bound by executive directives.
What’s new isn’t the intervention itself, but its form
One might argue that $26.7 billion is nothing compared to a market capitalization of around sixty trillion, and that most of the shares are non-voting. That’s true, but it misses the point. It’s not the size of the stake that matters, but the violation of competitive neutrality. The OECD ties government equity stakes to four conditions: transparent compensation for public contracts, equal treatment in regulation and procurement, no implicit government guarantees for debt financing, and a market-rate return requirement from the government as owner. Washington meets none of these. Intel, AMD, and Nvidia all received funding under the CHIPS Act; only in Intel’s case was it converted into government equity stakes. That is favoritism, not policy. And the market immediately priced it in: Trilogy Metals’ stock rose by about 240% following the announcement of the government stake, MP Materials’ by 150%, and Intel’s by 49%. These are not operational improvements, but rather the capitalized value of government favor, at the expense of their respective competitors.
The fact that Norway and Singapore hold government stakes without harming competition does not refute this; rather, it confirms it. In those countries, the government, as an owner, is bound by a publicly available mandate, return targets, independence from the government, and an obligation to eventually sell its stakes. The U.S. government is not subject to any of these constraints; rather, it is both a shareholder in one company and the regulatory authority for its competitors.
What does his mean for investors?
For investors, this is not a question of political persuasion, but of valuation. The U.S. market remains the freest among the major markets. But the government is no longer just a referee in that market – it is also a player.
Note: This text was translated using AI and may contain translation errors. The German version of the text is authoritative.