
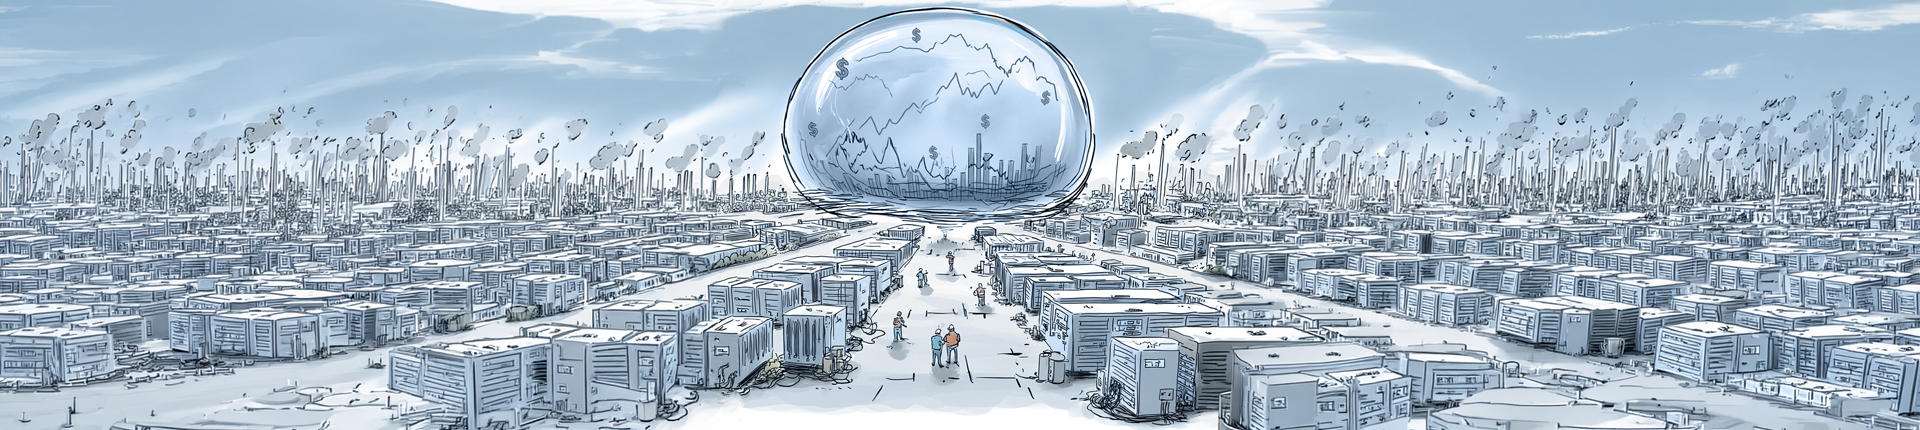

The physical side of an abstract revolution
When people talk about artificial intelligence, they think of models and software – something almost weightless. Those who finance it think of concrete, silicon, and electricity. Behind the intelligence revolution lies a construction boom of historic proportions: data centers with the energy demands of entire cities, built with sums of money never before raised in the industry. And everything about this story is true. The demand is real, the models deliver what they promise, and those who provide the infrastructure profit from it.
It is precisely this coherence that should make investors sit up and take notice, because a true story does not necessarily translate into a sound investment case. The more solid the operational reality becomes, the more readily the market extrapolates today’s growth far into the future. Whether this extrapolation holds up or whether a familiar pattern repeats itself is not a matter of conviction, but of scrutiny; and past cycles provide the benchmark here.
It's always the same pattern: growth, crash, exploitation
Infrastructure-driven technological revolutions follow a recurring pattern. The trigger is followed by a phase of land grabs. Companies secure market share before the boundaries are drawn. During this phase, capital flows in to secure the best position and out of fear of being left behind – questions about returns come later. Equipment suppliers benefit from this. The “shovel sellers” post explosive sales, and their valuations soar the most.
Then capacity outpaces demand. Returns fall, but intense competitive pressure keeps spending high, and this is exactly how overcapacity arises. Eventually, demand disappoints or funding dries up; prices and returns on investment plummet, and value corrections follow. Equipment suppliers are then hit the hardest, because demand does not gradually decline but abruptly collapses.
What happens next is crucial. The infrastructure is real and permanent, so it will be used. This can be seen, for example, in the “dark fiber” laid in 1999 – large quantities of unused fiber-optic cable. It wasn’t until the following decade that it was put into operation – and not by the original builders. The productivity gains flow to a new group of companies that build on the now-inexpensive infrastructure, while many of the original investors have disappeared from the market.
This pattern has a name: Economist William Janeway calls it a “productive bubble.” In this scenario, capital is destroyed, but the economy is permanently transformed. The shale gas boom is one of the most recent examples. Between 2010 and 2020, North American producers generated over $189 billion in negative free cash flow. Investors lost money, while cheaper energy eased the burden on household incomes. A systemic crisis did not materialize because the losses were spread across many small producers. This is the central theme of this article: What is good for the economy can ruin individual investors.
Cisco serves as a cautionary example of this lesson, illustrated by a single stock chart. The company was the dominant, highly profitable “shovel seller” of the Internet revolution. Anyone who bought the stock at its peak in March 2000 took twenty-six years to recoup their nominal investment; it wasn’t until early June 2026 that Cisco surpassed its dot-com high again, and in real terms, investors are still in the red today. The irony of the story: The catalyst that closed the decades-long price gap is, of all things, the next capex supercycle – this time for AI.
The bottom line is that being right about the technology is not the same as making money from it.
Four markers for a bubble
Instead of simply claiming that we live in a bubble, we propose a diagnostic tool: observable indicators that distinguish a healthy expansion from a severe bubble. Three indicators assess supply, and one assesses demand; only the last one can trigger a downturn.
Three markers on the supply side
Marker 1 – Financing structure
Who pays, and can the money be cut off?
In the case of the telecom bubble, the core of the problem was debt: Over two thousand network operators relied on debt and supplier financing and fell by the wayside when the markets consolidated between January and April 2001.
Today, however, the core consists of a handful of large, financially strong hyperscalers that finance their investments primarily from operating cash flow (Amazon projects around $200 billion for 2026, while Alphabet and Meta are in the high three-digit range). It won’t be as easy to cut them off as it was in 1999.
Preliminary finding: the core is green.
The deterioration in issuers’ financing structures is a side issue here. In 2025, the five largest hyperscalers raised more than three times their usual amount of debt; free cash flow is shrinking, while investments are doubling. Above all, debt is shifting off-balance-sheet: more than $120 billion in infrastructure debt was transferred off the balance sheets via special purpose vehicles (SPVs). One revealing case involves a special-purpose vehicle that received an investment-grade rating even though the operator behind it is in the high-yield segment. And the first cracks are appearing: a major private lender withdrew from a project worth billions, and a high-profile site expansion was canceled. These are still isolated cases, but this is precisely where the chain broke last time.
Findings: A green core, creeping debt at the edges; the early signs of fragility that swept through the periphery during the telecom bubble.
Marker 2 – Revenue quality
Does the cycle close with external, revenue-generating cash flow?
During the telecom bubble, equipment manufacturers lent their customers money to purchase their own technology and recorded it as revenue. Lucent, for example, committed approximately $8 billion in customer financing, and at Nortel, financing offers even reached 130% of the purchase price. Money flowed from the financing side into the equipment manufacturers’ revenue line, and the growth looked spectacular.
The modern echo of this is the circular interdependence of chip manufacturers, AI labs, and cloud providers, in which one’s investment becomes another’s revenue.
But not every such interdependence is dangerous. The litmus test that distinguishes legitimate concern from scaremongering is this: Does the cycle ever close with external, paying cash flow? If the loop ends with a profitable customer, it acts as an accelerator; if it ends in euphoria and a balance sheet that never sustains itself, it is ruinous. Which scenario unfolds is determined by the demand side.
Findings: Yellow; the structure is present, and its level of risk depends on marker 4.
Marker 3 – Cost side and key performance indicator
Does the valuation take into account the actual costs and the actual useful life of the asset?
EBITDA excludes depreciation as if it were non-cash. That may hold true for a building that stands for forty years, but not for graphics processors, which become obsolete in two to three years and are depreciated over five to six years. For an asset on the depreciation conveyor belt, the annual loss of value is a real, recurring cost: you have to replace the chips to stay in the race. Two factors exacerbate this.
First, purchases are made at the peak of the cycle. For hyperscalers, not investing seems more dangerous than overinvesting – so they buy, paying almost no attention to the price. And the price is high: producer prices for semiconductors are at an all-time high. Electricity is also becoming more expensive, as grid prices have skyrocketed in U.S. regions with a dense data center landscape.
Inflation becomes visible at the end of the value chain: In June 2026, Apple raised prices for Macs and iPads by up to $300 and explicitly cited the cost of memory chips for its AI expansion; Microsoft followed suit with its consoles. A cost base built up at the peak permanently lowers the return on investment and increases any subsequent write-downs.
Second, today’s profits primarily reflect how much is being invested – not what those investments actually cost. This distortion is symmetrical: what drives prices up destroys them just as quickly by driving them down. A dominant storage manufacturer recently saw its revenue jump by nearly 200%, but 85 to 90% of that was driven by price.
For a heavily leveraged cloud provider, the return on investment is already close to zero simply because of the generous depreciation period. As soon as a shorter, more realistic lifespan is assumed, it turns negative. And the market is already shifting: rental prices for the penultimate generation of chips fell by about 28% in one year.
Findings: Red in the area of key performance indicators, most pronounced in the outlying areas.
The demand-side marker
Marker 4 – Demand
The actual trigger.
One thing connects supply and demand: today’s shortage. It drives up costs but limits short-term overcapacity, because you can’t build capacity you can’t procure. It also doesn’t solve the problem – it merely postpones it.
This is most evident on the supply side: The three dominant storage manufacturers are currently expanding their capacity simultaneously and on a massive scale; if the plants reach volume production starting in 2027, it will be the largest simultaneous expansion in the industry’s history.
Every decision in this context is rational because capacity is sold out. Yet collectively, this behavior in the storage industry has invariably led to overcapacity and a price collapse – most recently in 2022–23, and before that in 2018–19. It’s the same dynamic as when “dark fiber” suddenly came online: scarcity today, overcapacity tomorrow.
But only demand can trigger the downturn. The telecom crash began with the debunking of a demand myth: the claim that data traffic doubles every hundred days was off by about an order of magnitude, and in the end, only a fraction of the fiber-optic capacity was actually in use.
The same question arises with regard to AI: How much of the demand represents real, paying, sustainable cash flow, and how much is capacity based on mere assumptions?
Depreciation acts as a stopwatch – it starts ticking the moment a chip is purchased, regardless of whether it’s already generating revenue. And it ticks quickly: Every new investment in chips immediately adds to depreciation expenses, while AI revenue grows only slowly. Ongoing investments alone generate more depreciation expenses than current AI revenues can cover. To make up for this, revenues would have to roughly double.
An external analysis confirms this sobering reality: If we take the consensus estimates through 2030 and assume zero costs, the implied return on investment for nearly all major hyperscalers is strongly negative, with the notable exception of Amazon. To achieve a 10 percent return, they would need to generate an additional two to five trillion U.S. dollars in annual revenue, compared to about one and a half trillion today.
And it is precisely this exception that is revealing. Amazon is in a better position not because of superior technology, but because of the model behind it: With AWS, investments fuel a business that has long been leasing its capacity to paying customers outside the AI cycle – precisely the external, paying cash flow from Marker 2. So it’s about the business model and the capital cycle, not the technology.
We must confront the strongest counterargument head-on: The relevant market size is not companies’ IT budgets, but the global market for cognitive work – which is many times larger. In that case, AI is not selling the tool, but the work itself, and the benchmark is no longer the price of the software, but the salary that would otherwise have to be paid.
But this view has its limits. Substitution only takes effect when the cost per result falls permanently below the price of human labor. That is not the case. What we’ve seen so far is supplementation, not replacement: AI boosts the productivity of experts, but beyond the realm of reliable tasks, it actually worsens results. Recognizing this requires precisely the kind of expertise that runs counter to the substitution thesis.
The real question is a race: Will the cost per result fall below the price of human labor – and will this happen before the depreciation schedule forces value adjustments?
Findings: As long as this remains open, Marker 4 remains the yellow signal, and the only one that can trigger the downturn.
Conclusion
Taken together, the indicators do not paint a clear picture of the overall mood, but rather reveal a diagnosis: healthy at its core, yet cause for concern at the periphery. The technology itself will prevail, and the systemic core is on firmer ground than it was in 1999 – namely, debt-free and self-financed. However, returns are unevenly distributed, and the areas of risk can be clearly identified:
- developers who rely on debt financing, who stake everything on a single, rapidly depreciating asset and finance it based on mere projected revenue;
- the valuations that exclude actual depreciation;
- capacity based on assumed demand rather than actual demand.
Anyone who wants to be part of the revolution is best off investing in the portion of capital that can weather a dip in demand: the self-financed core and the true bottleneck suppliers, not the debt-financed periphery. And they shouldn’t pay the prices of long-lived assets for a technology that is, in reality, on the depreciation conveyor belt.
The infrastructure that has already been built will ultimately be used; the question is not whether the technology will prevail, but whether the investor can weather the period during which the market realizes that he has gotten ahead of himself.
The technology is real. The capital cycle is the danger. And this danger is concentrated where it can be identified.
Note: This text was translated using AI and may contain translation errors. The German version of the text is authoritative.